
Last updated: September 2026 · Reviewed by Miguel Cibeira
This article is for informational purposes only and is not investment advice. See our full Disclaimer for details.
A common mistake we see: an investor checks an ETF’s average daily volume, sees a small number next to it, and decides the fund must be hard to get in and out of. Sometimes that’s true. Often it isn’t. ETF liquidity works differently from stock liquidity, and the difference matters if you’ve ever avoided a fund — or worse, overpaid to trade one — based on the wrong number.
The Two Kinds of Liquidity Nobody Explains
An ETF actually has two separate layers of liquidity, and only one of them is visible on a stock screener. The first is on-screen liquidity — the number of ETF shares that trade on the exchange each day, the same volume figure you’d check for any stock. The second is underlying liquidity — how easily the actual securities held inside the ETF’s portfolio can be bought and sold.[2]
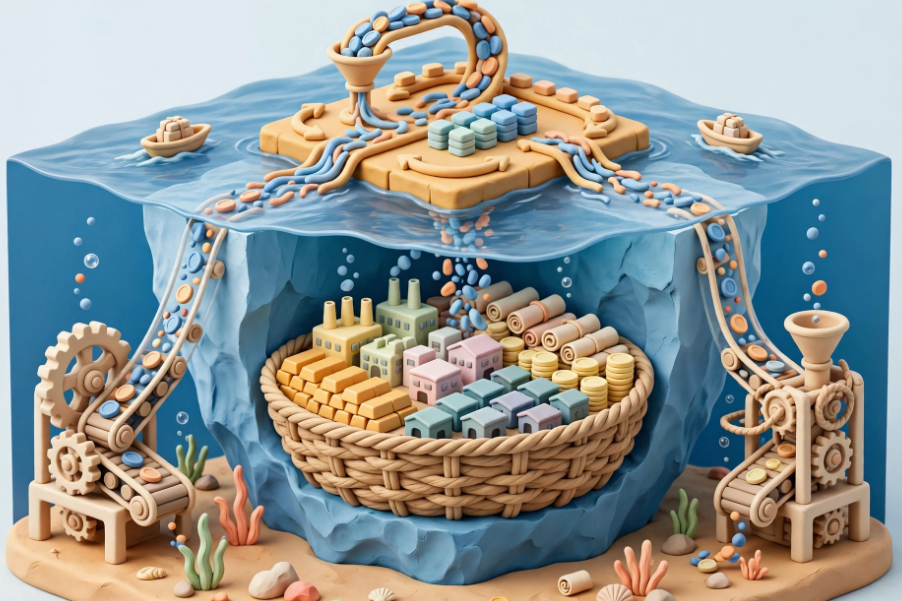
These two numbers can point in completely different directions. An ETF can trade a modest 20,000 shares a day on-screen while holding a basket of the most liquid large-cap stocks in the world — in which case its real liquidity has almost nothing to do with that 20,000 figure. What determines whether you can trade it efficiently is the liquidity of what’s inside it, not how many people happened to trade the wrapper that day.[2]
How Authorized Participants Create Liquidity on Demand
The reason underlying liquidity matters more than on-screen volume comes down to a mechanism most investors never see: creation and redemption. Large institutions called Authorized Participants (APs) can assemble the exact basket of securities an ETF holds and exchange that basket directly with the fund issuer for a block of new ETF shares — typically a minimum of 25,000 shares at a time, known as a creation unit. They can also run the process in reverse, handing back ETF shares for the underlying basket.[3]
This means an ETF isn’t limited to whatever shares already happen to be in circulation. If demand for an ETF spikes and pushes its market price above the value of its holdings, an AP can buy the underlying stocks, deliver them to the issuer, and receive new ETF shares to sell — pocketing the difference and, in the process, pulling the ETF’s price back in line with its net asset value. The reverse happens when the ETF trades below its underlying value. This constant arbitrage is what keeps an ETF’s price tethered to what it actually owns, and it’s also what lets an AP create a large order’s worth of shares on the spot rather than waiting for enough natural sellers to show up on the exchange.[3]
A Real Example: Same Stocks, Very Different Volume
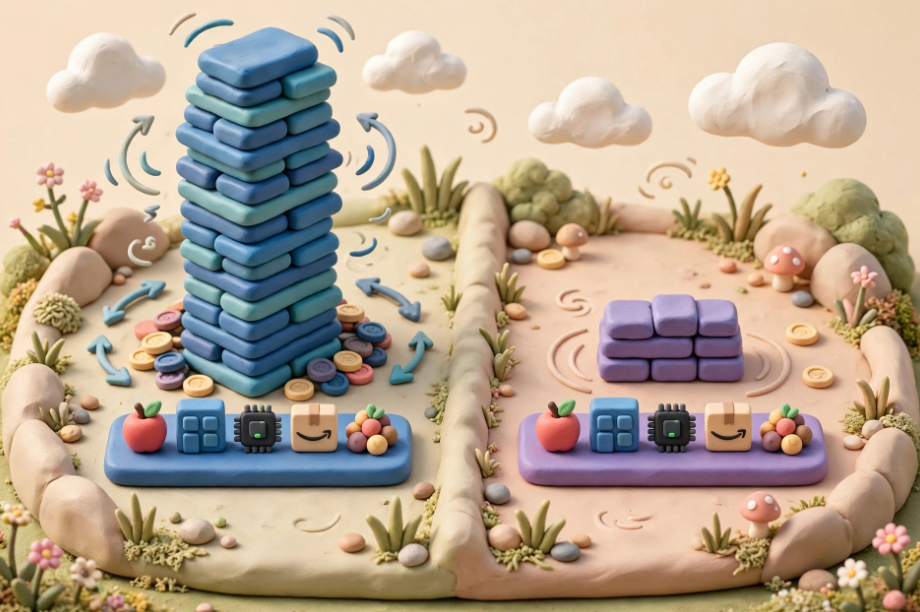
Three of the largest S&P 500 ETFs on the market — SPDR’s SPY, iShares’ IVV, and Vanguard’s VOO — all track the identical 500 stocks. SPY typically trades a dramatically higher on-screen volume than IVV or VOO, simply because it’s more popular with short-term traders and options traders. If on-screen volume were the whole story, IVV and VOO would look meaningfully less liquid than SPY. In practice, all three trade with tight bid-ask spreads and can absorb large institutional orders without much price impact, because their liquidity comes from the same 500 large, easily-traded stocks underneath — not from how many of their own shares changed hands that particular day.
The Bid-Ask Spread Is What Actually Costs You
If on-screen volume is an unreliable liquidity signal, what should you actually look at? The bid-ask spread — the gap between the highest price a buyer is offering and the lowest price a seller will accept. A narrower spread means a lower real cost to trade, regardless of the fund’s headline volume. Volume and spread are related — heavily traded ETFs tend to have narrower spreads — but volume alone doesn’t set the spread; the liquidity of the underlying holdings does.[1]
The practical risk of ignoring the spread and focusing only on volume shows up most with large orders. Even a stock with a tight quoted spread can move against you if you try to buy far more shares than are available at that price — a cost known as market impact. ETFs largely sidestep this problem for the same reason described above: if your order is large enough, an Authorized Participant can create new shares to fill it directly, rather than forcing you to chase a thin order book.[1]
When Low Volume Actually Is a Warning Sign
None of this means volume is irrelevant — it means you have to ask what’s driving it. Low on-screen volume is genuinely a red flag when the fund’s underlying holdings are also illiquid: a leveraged or inverse ETF, a thematic fund concentrated in obscure micro-cap stocks, or an ETF holding thinly-traded emerging-market or frontier-market equities. In those cases, both layers of liquidity are thin at the same time, and the Authorized Participant mechanism can’t manufacture liquidity in securities that don’t have any to begin with. That combination — low volume plus genuinely illiquid holdings — is where wide spreads and real trading costs show up.
International ETFs add one more wrinkle worth knowing: when the underlying market is closed (due to time zone differences), U.S.-listed ETFs holding those stocks can trade with wider spreads during U.S. hours, since market makers are pricing in some uncertainty about where the underlying securities will open next.
A Practical Checklist Before You Trade
- Check the spread, not just the volume. A narrow bid-ask spread is a better real-time liquidity signal than the daily share count.
- Use limit orders, especially for less-common ETFs. A limit order caps the price you’ll pay or accept; a market order on a wide spread can execute at a worse price than you expected.
- Avoid trading in the first and last few minutes of the session. Spreads tend to widen right at the open and close, when prices are still settling.
- Know what’s actually inside the fund. An ETF holding large, widely-traded stocks or bonds is generally liquid regardless of its own trading volume; one holding niche or thinly-traded assets is a different story.
- For unusually large orders, talk to your broker. Institutional-size trades can often be worked directly with a market maker or Authorized Participant to avoid moving the price.
References
- Fidelity, “Understanding an ETF’s spreads and volumes”.
- RBC Global Asset Management, “Understanding ETF trading volume and liquidity”.
- Schwab Asset Management, “Understanding the ETF creation and redemption mechanism”.
This article is provided for general informational and educational purposes only and is not a recommendation to buy or sell any security. Fund and mechanism details referenced above reflect the sources cited as of the “last updated” date and are subject to change. Always do your own research and consult a licensed financial advisor before making investment decisions. Read our full Disclaimer and Privacy Policy for more information.
About the Author
Miguel Ángel Cibeira researches and writes every article on The Fund Atlas personally, sourcing data directly from fund issuers, the IRS, the SEC, and the Federal Reserve. He is not a licensed financial advisor, broker-dealer, or RIA — this site offers independent research and general information, not personalized financial advice. Read the full bio →