
Last updated: September 2026 · Reviewed by Miguel Cibeira
This article is for informational purposes only and is not investment advice. See our full Disclaimer for details.
A leveraged ETF that promises “2x the S&P 500” sounds like it should do exactly that — double the index’s return, in either direction. Over a single day, it roughly does. Over a month, a quarter, or a year, it usually doesn’t, and the gap isn’t a bug, a fee, or a scam. It’s basic math about what happens when you multiply a return every single day instead of once. Anyone holding one of these funds for longer than they realize should understand exactly why, because the U.S. Securities and Exchange Commission has been warning about this specific mechanism for over a decade — and the warning still catches people off guard.
What “Leveraged” and “Inverse” Actually Promise You
A leveraged ETF (commonly a 2x or 3x fund) is built to deliver a multiple of an index’s return on a given day. An inverse ETF is built to deliver the opposite of an index’s daily return, and a leveraged inverse ETF combines both — aiming for a multiple of the opposite move. Funds like this exist across nearly every asset class covered elsewhere on this site, including leveraged Bitcoin futures ETFs, and they typically use swaps, futures contracts, and other derivatives rather than simply holding more shares of the underlying stocks — which is part of why they carry higher fees and different tax treatment than a standard index fund.
The word doing the real work in that description is “daily.” These funds aren’t designed to deliver double the index’s return over a week, a month, or a year — only over a single trading day. What happens when you string many of those daily resets together is where most investors’ expectations and the fund’s actual behavior start to diverge.
The Daily Reset: Why the Math Doesn’t Stay Simple
To deliver its stated multiple every single day regardless of what happened the day before, a leveraged ETF has to rebalance its exposure daily — buying more exposure after a gain, trimming exposure after a loss, so that tomorrow’s 2x (or 3x) target is calculated fresh off today’s new, reset value. That daily rebalancing is exactly what breaks the intuitive “just multiply the long-term return” assumption. Returns don’t add up in a simple, linear way when they compound — they multiply, one day at a time, and multiplying a sequence of ups and downs produces a different result than multiplying a single average return.
This effect is often called volatility decay or “beta slippage,” and it gets worse — not better — the more a market chops sideways with big daily swings in both directions. A market that grinds steadily in one direction with low daily volatility causes relatively little divergence. A market that whipsaws up and down, even if it ends up roughly flat, can cause a leveraged fund to lose a meaningful amount of value purely from the mechanics of daily compounding — independent of any fees.
Real Numbers From the SEC’s Own Warning to Investors
This isn’t a theoretical risk pulled from a textbook. The SEC and FINRA jointly published an Investor Bulletin specifically on this topic, and it includes real, worked examples of exactly how far the divergence can run. In one example cited in the bulletin, an index gained about 2% over a four-month period — and over that same stretch, a 2x leveraged ETF tracking it fell 6%, while a 2x inverse ETF on the same index fell 25%. In a separate, more volatile example, an index gained roughly 8% while a 3x leveraged fund tracking it fell 53%.
Source: U.S. Securities and Exchange Commission & FINRA, “Updated Investor Bulletin: Leveraged and Inverse ETFs.” The bulletin states plainly that most of these funds “reset daily, meaning that they are designed to achieve their stated objectives on a daily basis,” and that their performance “over longer periods of time…can differ significantly from the stated multiple of the performance of the underlying index or benchmark.” The regulators’ own conclusion is direct: these products are generally unsuitable for anyone planning to buy and hold them the way you might hold a core index fund.
A Simplified Example You Can Trace by Hand
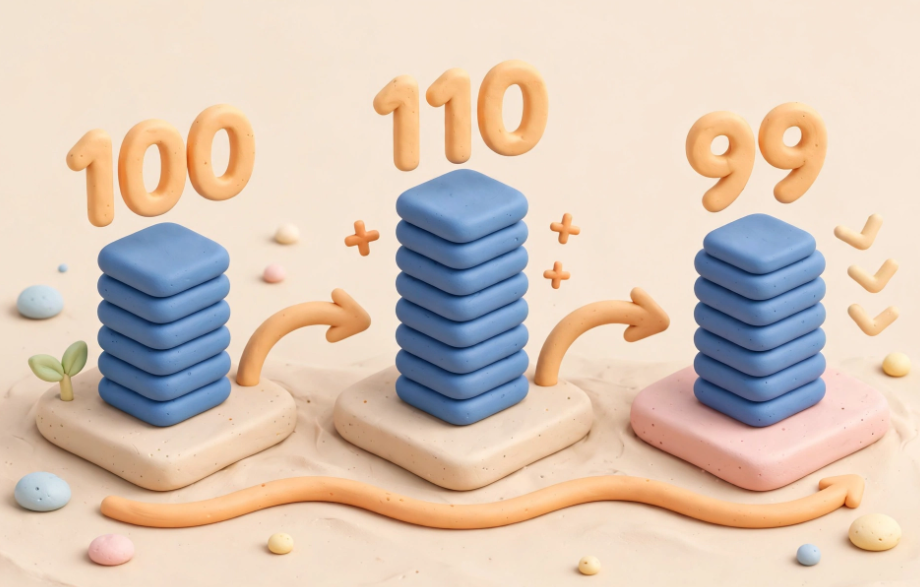
Real markets rarely move in the clean back-and-forth pattern below, but working through one by hand makes the mechanism concrete. Imagine a hypothetical index at 100, and a hypothetical 2x fund also starting at 100 (ignoring fees and financing costs, which would make the real-world gap even larger):
- Day 1: Index +10% → 110.00. Fund +20% → 120.00.
- Day 2: Index -10% → 99.00. Fund -20% → 96.00.
- Day 3: Index +10% → 108.90. Fund +20% → 115.20.
- Day 4: Index -10% → 98.01. Fund -20% → 92.16.
After four days of the index alternating +10%/-10%, the index itself is down 1.99% (98.01 versus a starting value of 100) — simple compounding already means it isn’t back at exactly zero. If the 2x relationship held over the full period the way it holds on any single day, you’d expect the fund to be down roughly twice that, around 3.98%. Instead, the fund is down 7.84% — nearly double the “expected” gap, purely from resetting its 2x exposure fresh every single day. Nothing went wrong; the fund did exactly what it was designed to do each individual day. The multi-day result is simply a different, and less intuitive, calculation than most people assume going in.
Why This Isn’t “Rigged” — It’s Geometric vs. Arithmetic Returns
It’s worth being precise about what’s actually happening, because “the fund is designed to lose money” is a common but inaccurate way people describe this. The fund is designed to hit its stated multiple each day, and it generally does that accurately. What breaks down is the assumption that daily multiples chain together into the same multiple over longer periods — an assumption that would only hold if returns added together in a straight line instead of compounding. This is the same underlying idea covered in our volatility guide: a fund’s swings in both directions, not just its direction, shape its actual compounded outcome, and that effect is dramatically amplified once daily leverage is layered on top.
What These Funds Are Actually Built For
None of this makes leveraged or inverse ETFs inherently illegitimate — it makes them tools built for a specific, short time horizon rather than the buy-and-hold approach this site generally covers, as in our guide to ETFs actually worth holding long-term. They’re designed for traders looking to express a short-term, tactical view — often a single day or a few days — and who plan to actively monitor and rebalance the position themselves, not for someone contributing to a retirement account on a set-it-and-forget-it schedule. A long time horizon, the kind that younger investors are often told to lean into, is precisely the condition under which daily-reset compounding does the most damage to a leveraged position.
Before You Buy a Leveraged or Inverse ETF: A Checklist
- Know your holding period before you buy. If you can’t articulate why you’d sell within days rather than months, this probably isn’t the right tool.
- Read the actual prospectus. It will state the fund’s daily objective explicitly and typically includes its own compounding-risk disclosures.
- Expect higher costs. The derivatives and financing involved generally make these funds more expensive than a standard index ETF, and less tax-efficient.
- Sideways, choppy markets are the worst case, not calm directional ones. A market that swings hard in both directions erodes a leveraged position faster than one that trends smoothly.
- If you wouldn’t check the position daily, don’t hold it. This is the core, direct guidance from the SEC/FINRA bulletin itself, not an exaggeration of it.
This article is provided for general informational and educational purposes only and is not a recommendation to buy or sell any security. The hypothetical example above ignores fees and financing costs for simplicity and does not represent any real fund. Read our full Disclaimer and Privacy Policy for more information.
About the Author
Miguel Ángel Cibeira researches and writes every article on The Fund Atlas personally, sourcing data directly from fund issuers, the IRS, the SEC, and the Federal Reserve. He is not a licensed financial advisor, broker-dealer, or RIA — this site offers independent research and general information, not personalized financial advice. Read the full bio →